The debate is usually framed as a choice of philosophy: are you a product company or a sales company? That framing produces bad decisions, because the honest answer for most B2B businesses is that the model should be chosen segment by segment, not adopted wholesale.
The useful question is narrower. For this product, sold to this buyer at this price, who should do the work of proving the value: a person, or the product? This article compares the two models on that basis, looks at cost and scalability, and sets out how to run both without them undermining each other.
Quick Takeaway
- Sales-led and product-led growth answer the same question differently: who proves the value before money changes hands. The model that fits is usually decided by deal size and how much configuration your product needs before it is useful, not by preference.
Product-Led Growth Makes the Sales Conversation Optional
Product-led growth is a go-to-market strategy in which the product itself is the primary driver of customer acquisition, conversion and expansion, rather than the people on the sales and marketing teams.
That is the definition given by Blake Bartlett, who coined the term at OpenView in 2016, in a 2023 interview with Sacra. He is explicit that PLG is not anti-sales: sales still exists, but talking to a rep and signing a contract is not required in order to adopt the product. Our pillar guide to product-led growth covers the model in full.
Sales-Led Growth Puts People in Front of the Product
Sales-led growth is a go-to-market strategy in which people, usually sales reps supported by marketing, drive acquisition, conversion and expansion, and the customer typically experiences the product after a commercial process rather than before it.
It is still the dominant model in large parts of B2B, for good reasons. When a purchase is complex, expensive, politically sensitive or requires integration into existing systems, a person who understands both the product and the customer’s situation is genuinely valuable. A buying committee assessing a platform that will run a core process is not going to reach a decision through a trial account.
Six Differences That Decide Which Model Fits
| Dimension | Sales-led growth | Product-led growth |
| Who proves the value | A rep, through demos, pilots and business cases | The user, inside the product |
| When the first conversation happens | Before the product is used | After the user has seen value |
| Primary qualification signal | Firmographics and marketing engagement | Behaviour in the product |
| What growth costs | Headcount, roughly linear with volume | Product and infrastructure, with lower marginal cost per customer |
| Where budget goes | Sales capacity and demand generation | Product, onboarding and growth engineering |
| Typical entry point | A negotiated contract | A small purchase or free tier that grows |
Table 1: The core differences.
The budget row is the one that shows up in filings. Atlassian’s FY2024 annual report states that the company invests significantly more in research and development than in traditional sales activities relative to other enterprise software companies, and reports research and development expenses at 50% of revenue in FY2024 and 53% in FY2023. Its filing also says the company does not solely rely on a traditional commissioned direct sales force to land new customers, because its model focuses on self-service, data-driven targeting and automation, with its sales team focused primarily on expanding relationships with existing customers.
Product Experience and Sales Interaction Answer Different Questions
Both models have to resolve the same buyer questions. They just resolve them in different places.
| Buyer question | Answered in a sales-led model by | Answered in a product-led model by |
| Does this do what I need? | A tailored demo | Using the product on real work |
| Will it work in our environment? | A solutions engineer and a pilot | Integrations, documentation and a trial against real data |
| What will it cost at our scale? | A quote | Transparent pricing and usage limits |
| Can I trust the vendor? | The relationship with the rep | The product experience, plus peer and third-party evidence |
| How do I get my team on board? | A business case built with the rep | Inviting colleagues into the product |
Table 2: Where each model answers the buyer’s questions.
Notice that the product-led column depends on the product being genuinely usable on real work. Where it is not, the questions do not disappear. They resurface later, usually in a stalled trial.
The Buying Journey Has Moved Toward Self-Evaluation, But Not Away From People
Gartner reports that 75% of B2B buyers prefer a rep-free sales experience. 6sense’s 2025 B2B Buyer Experience Report, based on nearly 4,000 buyers, found that 94% of buyers ranked their shortlist by preference before engaging sellers, and that buyers initiated 79% of first conversations with sellers.
Two findings pull the other way, and both deserve to be quoted alongside the first. Gartner reports that self-service digital purchases are far more likely to result in purchase regret, and that B2B buyers are 1.8 times more likely to complete a high-quality deal when they engage with supplier-provided digital tools in partnership with a sales rep rather than independently. 6sense’s research found that in 85% of successful purchases buyers had prior direct experience with the vendor, and that sellers act as brand assets even in lost deals.
The reasonable conclusion is not that one model wins. It is that buyers want to evaluate independently and then talk to someone useful. We cover the buying-side shifts in The B2B Buyer Journey in 2026.
Cost and Scalability: Deal Size Usually Settles the Argument
Sales-led growth has a roughly fixed cost per deal. Whatever the contract value, a rep runs a discovery call, a demo, a pilot and a negotiation. That cost is bearable when the deal is large and prohibitive when it is small.
Product-led growth inverts the curve. The cost of serving one more self-service customer is close to the cost of the infrastructure they use, until they hit something that needs a person.
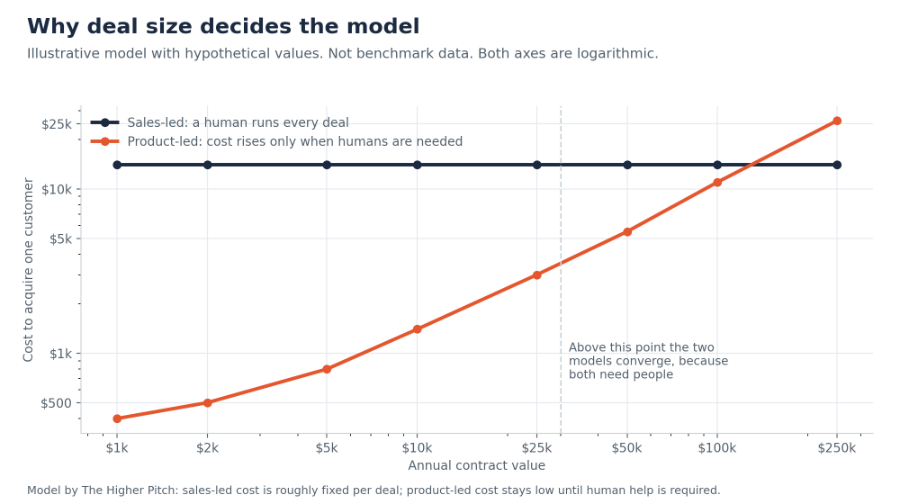
Figure 1: Illustrative model with hypothetical values, not benchmark data. The shape is the point: below a certain contract value, a human-run sales process cannot pay for itself; above it, the two models converge because both require people.
Two cautions about the economics:
Product-led growth is not cheap, it is differently expensive. The investment moves from sales headcount to product and engineering, and it is paid up front, before revenue arrives.
Free users are a cost, and most never convert. Atlassian’s own risk factors state that, historically, a majority of users never convert to a paid version from free trials or limited free versions. Planning a product-led motion on the assumption that most free users will pay is planning on the wrong premise.
When B2B Companies Should Use Each Model
| Situation | Lean toward | Why |
| The product is useful within one session, on real work | Product-led | The user can prove value without help |
| Deal sizes sit below typical procurement thresholds | Product-led | A human-run sales cycle cannot pay for itself |
| The product requires integration, migration or configuration to be useful | Sales-led | There is nothing for a self-service user to succeed at yet |
| The buyer is a committee that will never use the software | Sales-led | Value has to be argued, not experienced |
| Purchases require security review, procurement and legal | Hybrid | Users can adopt; people are needed to close |
| A large user base already exists with low paid conversion | Hybrid | Sales assist targets accounts already showing value |
Table 3: Choosing a model by situation.
Each committee role also reacts differently to a self-service motion, which is why hybrid designs tend to win in considered purchases.
| Committee role | What self-service gives them | What they still need a person for |
| End user | Hands-on proof that it solves their problem | Little, if the product is well designed |
| Champion | Evidence and internal credibility | Help building the business case for finance |
| Financial ratifier | Transparent pricing | Terms, invoicing and multi-year commitments |
| Technical evaluator | A real test against their environment | Architecture, security and integration answers |
| Procurement | Published terms to compare | Contracts, data processing agreements and negotiation |
Table 4: The buying-committee lens on self-service.
Hybrid Works When It Is One Journey, Not Two Funnels
Bartlett names the failure mode directly: the biggest problem when sales is layered onto PLG is viewing them as two separate funnels, or bringing in a sales leader who treats self-service as a lead source and abuses it, asking for more leads to call and abandoning anyone who does not convert. He argues that users can tell when they are being exploited for sales goals rather than given a good product experience, and that the right model is one continuous journey in which sales identifies the self-service ceiling and helps the customer get beyond it.
Four design decisions make a hybrid hold together:
- Define the self-service ceiling explicitly. Name the situations where a user genuinely cannot proceed alone: team rollout, SSO, security review, procurement, custom terms.
- Qualify on behaviour, not on sign-up. Use product-qualified lead criteria so reps contact accounts that have reached value, not everyone with an email address.
- Give reps usage context before the call. A conversation that starts from what the team has already built is a different conversation from a generic pitch.
- Compensate for assisting, not intercepting. If reps are paid only for deals they source, they will find ways to intercept self-service users who would have converted anyway.
The plumbing matters here too: usage events have to reach the CRM in a usable form, which is where most hybrid models stall. Our RevOps playbook and comparison of HubSpot and Salesforce for SaaS cover that ground.
A B2B Example: One Company, Two Motions
Consider a hypothetical API monitoring company selling to engineering teams. This is an illustration, not a client.
The starting point. Everything runs sales-led: a demo request form, a discovery call, a guided pilot and an annual contract. Win rates are respectable, but the company cannot profitably serve teams below a certain size, and competitors with free tiers are reaching those engineers first.
The change. The company keeps its sales-led motion for enterprise accounts and adds a self-service tier for individual engineers and small teams, priced transparently and purchasable by card. The trial covers one service with full features, because a partial product would prove nothing.
Where sales fits. Reps stop receiving every sign-up. Instead, an account becomes a product-qualified lead when it connects a production service, invites three teammates and crosses a usage threshold. At that point a rep reaches out with context about what the team has already instrumented.
What changes in measurement. The company reports the two motions separately: activation rate, free-to-paid conversion and time to value for self-service; win rate, cycle length and deal size for sales-led; and net revenue retention across both. The hard question it must answer honestly is whether self-service is creating new revenue or cannibalizing deals a rep would have won anyway.
To choose a motion for your own product, see 7 Product-Led Growth Examples, and to build one, see How to Build a Product-Led Growth Strategy From Scratch.
THP Studio Perspective
- The version of this debate we see inside companies is rarely strategic. It is territorial. Marketing wants a self-service motion because it promises growth without more sales headcount, and sales hears a plan to route its pipeline around it. Both sides then argue about philosophy when the real question is arithmetic: at your average deal size, can a human-run sales cycle pay for itself? If it can, PLG is an addition rather than a replacement. If it cannot, no amount of sales enablement will fix the economics, and the argument is already over.
Frequently Asked Questions
Key Takeaways
- Decide the model by deal size and product complexity, not by preference or by what competitors do.
- Quote the buyer research in full: buyers prefer rep-free evaluation, but self-service purchases carry more regret and hybrid engagements are associated with higher-quality deals.
- Expect product-led growth to move cost rather than remove it, and to require investment before revenue.
- In hybrid models, define the self-service ceiling and let behaviour, not sign-up, decide when a rep gets involved.
- Compensate reps for assisting rather than intercepting, or the hybrid will quietly revert to a sales-led funnel.
Work With THP’s Campaigns & Demand Generation Studio
- THP’s Campaigns & Demand Generation Studio builds B2B demand programs around pipeline and revenue rather than lead volume, including for companies running self-service and sales-led motions side by side. If you are deciding where each motion should own the customer, we can help you map it.
Author